After years of buildup, we’re finally starting to see what the US metal additive manufacturing (AM) market could look like at scale. To be sure, it’s still not quite there, outside certain pockets of robust growth. But the groundwork has been laid, and features of a mature market are gradually starting to emerge.
One takeaway is that OEMs should kindly move off center stage and let the services and materials markets have their time in the sun. Along those lines, AM Research’s Scott Dunham has been writing about how he’s revamped his approach to the services market (this is relevant to a new services report which is available now — ahead of its publication at the end of 2026 or beginning of 2027 — at a discounted price).
The changes going on in the materials market, with metals in particular, are just as important, and are intertwined with what’s going on with services. That interrelated theme is on display in a new deal announced by 6K Additive and ADDMAN. Over 30 months, ADDMAN will purchase between $8.1 million and $10.8 million worth of Nickel 718 from 6K, an agreement which includes “a structured revert buy-back program” that will return revert powder to 6K in alignment with 6K’s circular supply strategy.
According to the announcement, ADDMAN’s powder contract will support its growing metal AM activity in the aerospace, defense, and energy markets. Knowing the terms of the deal, for me, is what’s most valuable here, as material supply agreements are (from my perspective, at least) still fairly unknown entities for those following the AM industry. But it is also quite valuable to be able to quantify precisely how much strategic drivers like aerospace and defense are stimulating metal AM demand, and this kind of information definitely helps.
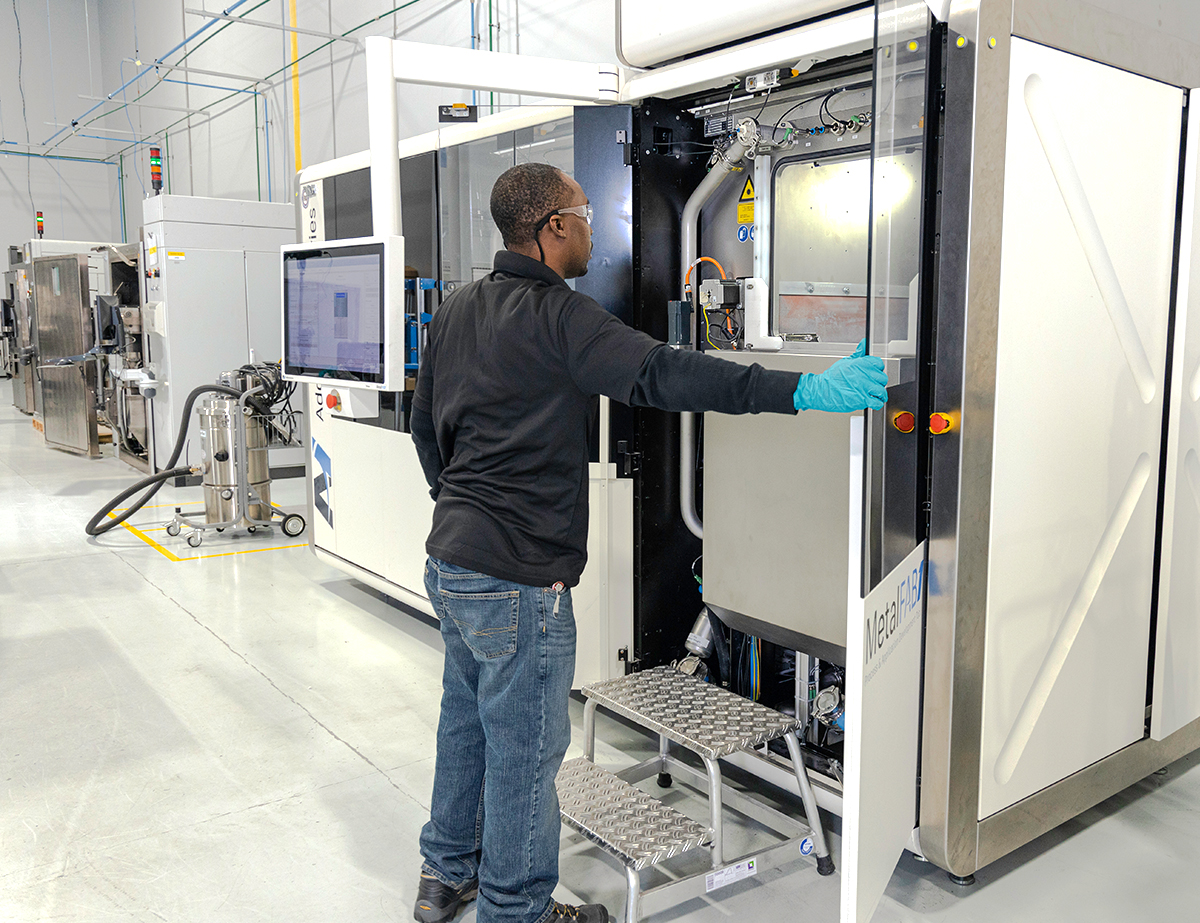
Image courtesy of ADDMAN
And, it is nice to see energy included with aerospace and defense as one of those demand catalysts. I just wrote about why I think energy is poised to get a push from global public-private power brokers that’s similar to the one that’s accelerated the defense sector’s AM adoption in recent years. However, that can only happen with a parallel alignment between companies like 6K and companies like ADDMAN, and, of course, their own respective customers.
Now, while I said that OEMs should move off center stage, it is also worth mentioning that ADDMAN just announced a sizable purchase of new HP Multi Jet Fusion systems: 81 of them, bringing their total fleet to 125. While that is a polymer market story, it does further reinforce the idea that ADDMAN is making meaningful investments in production capacity.
Along those lines, it’s noteworthy that this deal involves a single alloy. As the market continues to develop over the next couple of years, as both companies spot similar potential with other metals, and as both gain awareness of the benefits of a circular supply chain, there’s no reason why the relationship can’t expand to include other materials. Aside from whatever positive results for 6K and ADDMAN that would entail, it would provide indispensable visibility into what verticals and applications are shaping the AM market.
So, pay attention to any information that gets divulged about the relationships between service providers and materials suppliers. This is where we should expect to learn the most about how the metal AM market is growing.
Featured image courtesy of 6K Additive